Penny, our cash application digital employee
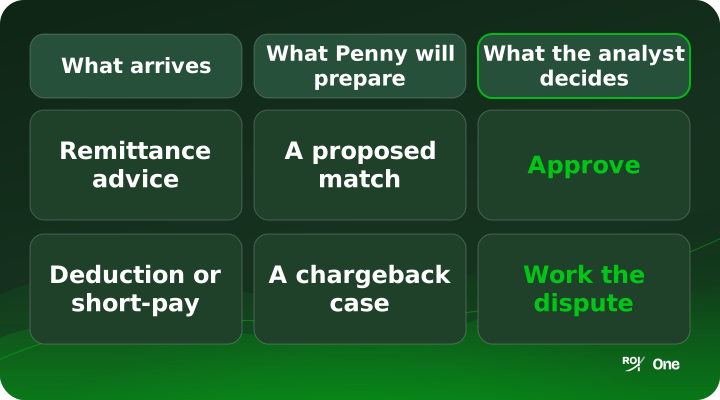
Penny will match remittance advices to open invoices. An analyst approves each match first.

What cash application is
Cash application is matching each payment you get to the open invoices it pays. A wholesaler selling to retailers gets each payment with a remittance advice listing what it covers. Short-pays and deductions are part of that.
ROIAI One will offer cash application through Penny, a managed digital employee. It's in early access and in build, not live.
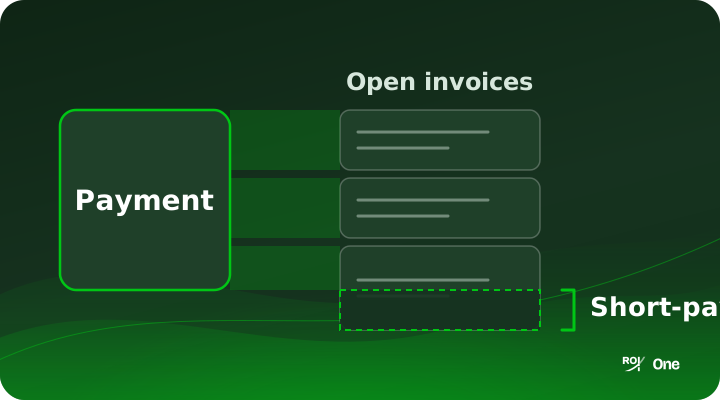
What Penny will do
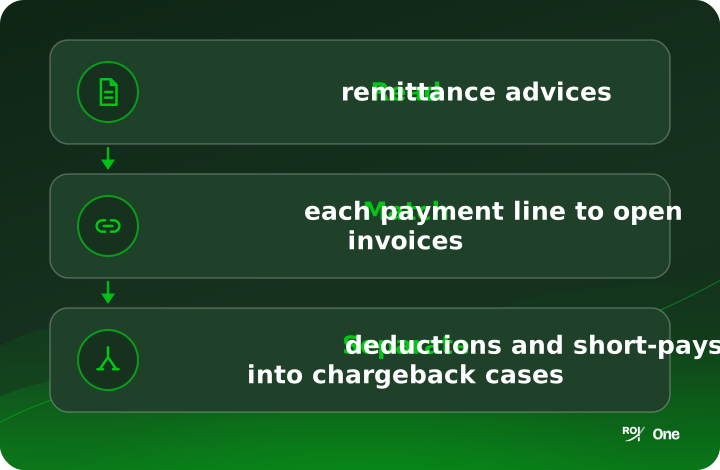
Penny will do three jobs with every remittance advice:
- Read remittance advices that arrive by email or in retailer portals.
- Match each payment line to the open invoices it pays.
- Separate every deduction or short-pay into a chargeback case.
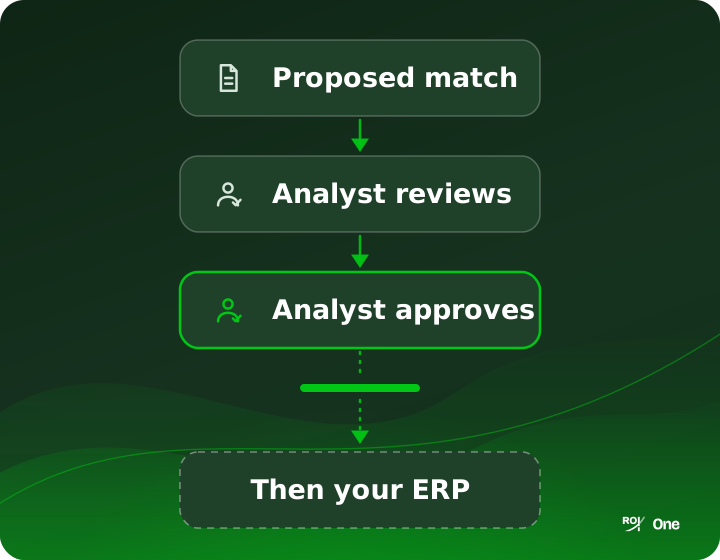
An analyst reviews each proposed match before anything posts to your ERP.
How an analyst stays in control
An analyst reviews each proposed match and approves it before anything posts to your ERP. Your team keeps control of the ledger, not software.
Penny proposes. The analyst decides. Nothing will post until a match is approved.
Where short-pays go
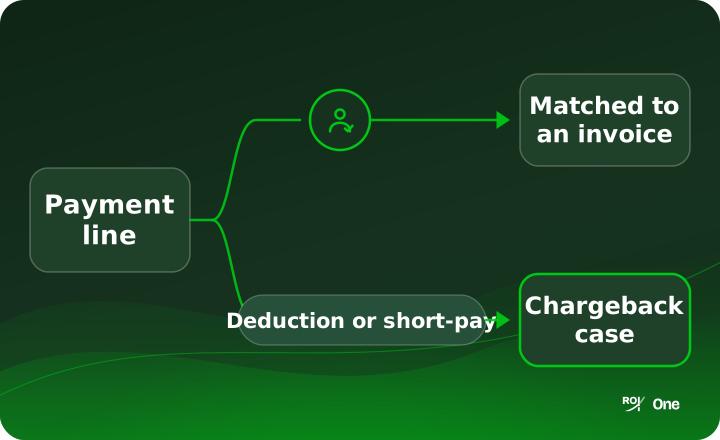
Every deduction or short-pay will become its own chargeback case. It's worked as a dispute, not left in unapplied cash.
A short-pay is a payment that covers less than the invoice. A deduction is an amount a retailer takes off a payment. Unapplied cash is money received that isn't yet matched to an invoice.
See chargeback recovery and the reason code library.
Who it is for
Cash application is for wholesalers that sell to retailers and apply payments by hand. It also fits teams where finance and chargeback work sit in different hands.
Design partners
Penny is in early access, taking design partners. It's in build and isn't running for any customer yet.
If your team applies payments by hand and wants a say in how it's built, talk to us.
Questions
Can I use cash application today?
- Penny is in early access for design partners. It's in build, and it isn't running for any customer yet.
Does an analyst review the matches?
- Yes. An analyst reviews each proposed match and approves it first.
What happens to a deduction or short-pay?
- Penny will separate it into a chargeback case, so it's worked as a dispute.
Where does Penny read remittance advices?
- From email or retailer portals.
Will Penny post to my ERP on her own?
- No. Nothing will post to your ERP until an analyst approves the match.
How do I become a design partner for cash application?
- Select Talk to us on this page. We'll talk it through with you.
Help shape cash application
Cash application is in build. Join us as a design partner.